Axios Markets
September 21, 2026
1 big thing: AI is becoming too interconnected to fail
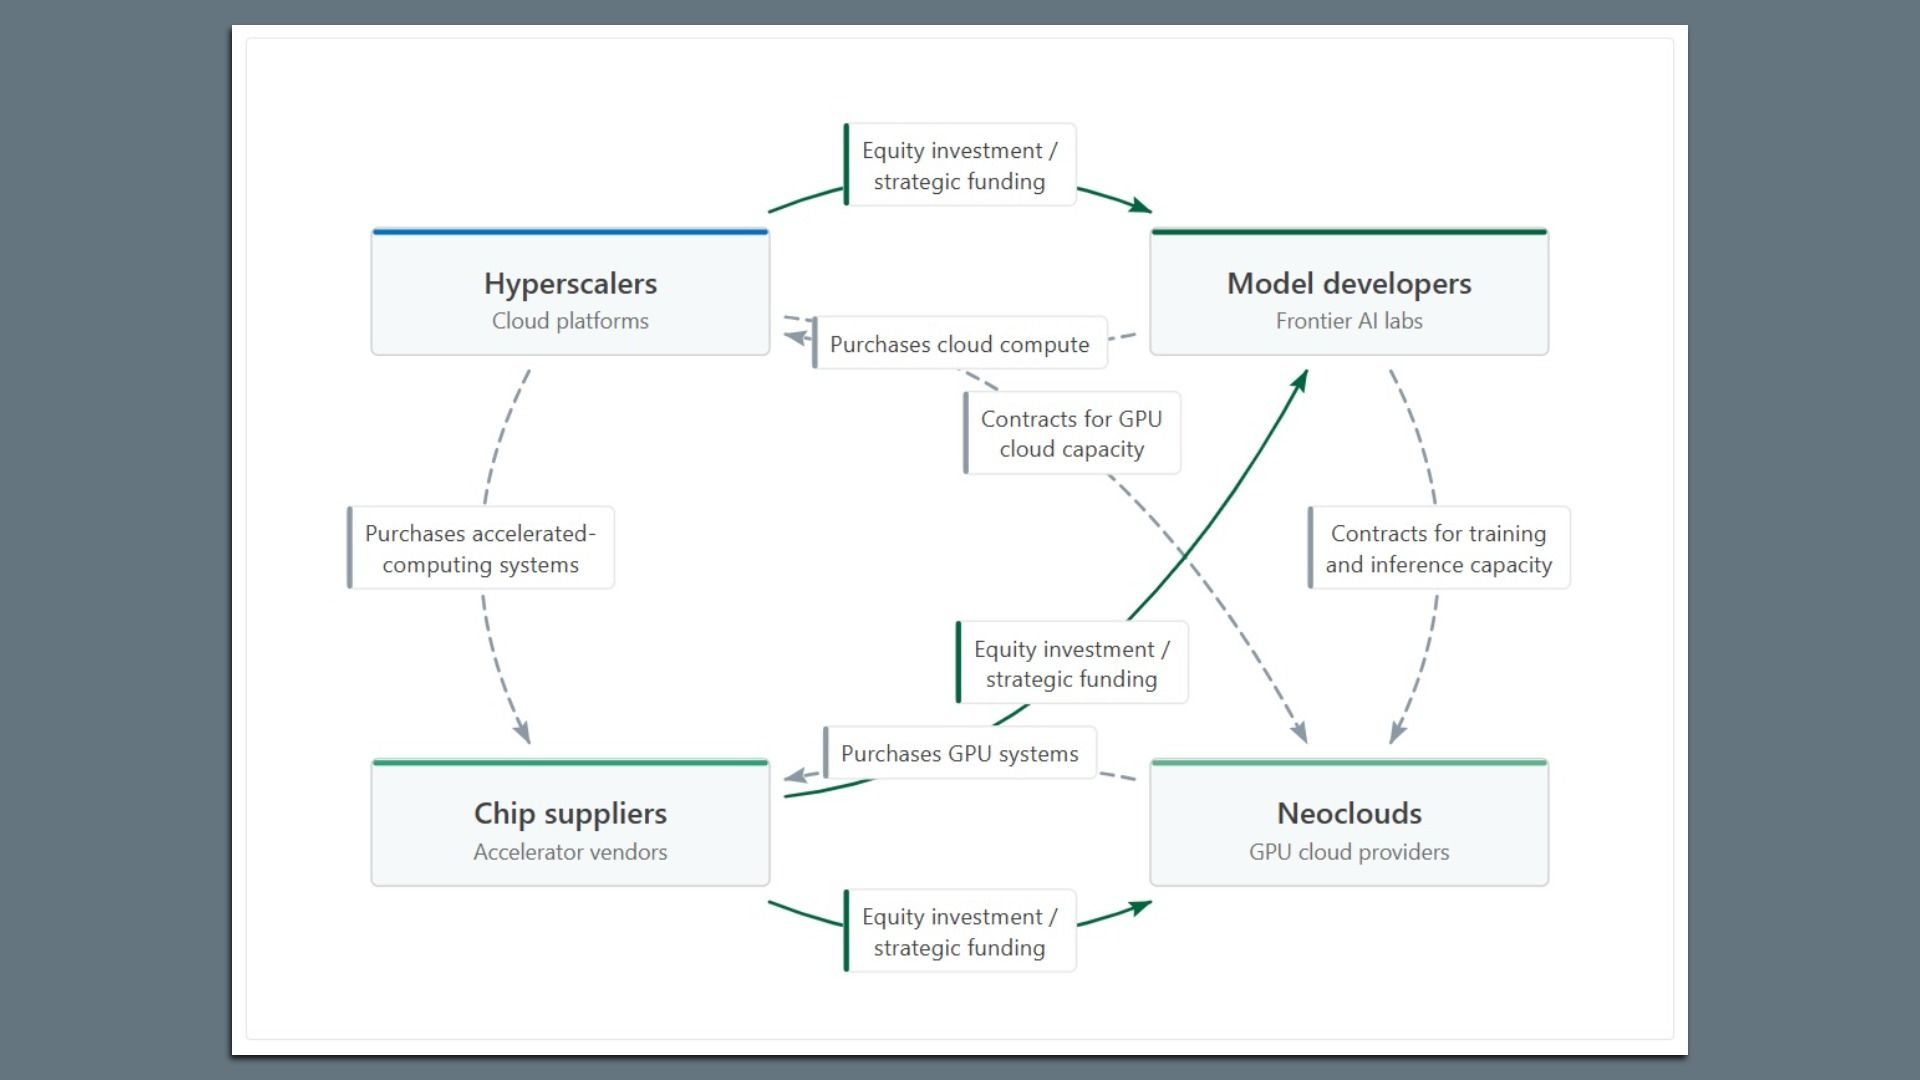
The AI buildout is so interconnected that a single point of failure could ripple across the multitrillion-dollar sector, a new analysis finds.
Why it matters: AI investment is powering the U.S. economy, and any stumble would likely have a big impact.
- The idea that reining in AI development could "crash" the markets and lead to a recession is a reason President Trump has taken an anti-regulatory, anti-slowdown approach, the New York Times reports.
State of play: The situation mirrors, in some ways, the mortgage market in the build-up to the financial crisis, say the authors of a new paper, highlighted in the Financial Times, from London-based Sona Asset Management.
- "Opaque and concentrated exposures, counterparties linked in complex ways that few have mapped, and demand part-underwritten by the same balance sheets that depend on it," they wrote.
The big picture: The analysis comes on the heels of S&P's warning that hyperscaler credit quality is weakening.
- It also arrives at a time when borrowing costs are rising everywhere, including in the AI sector, which has billions of dollars in borrowing on the line.
Where it stands: Sona maps out the complex AI ecosystem, a fast-growing supply chain comprising 255 public companies: the big hyperscalers like Microsoft and Meta, chipmaking behemoth Nvidia, and many smaller players like data center operators and neoclouds that rent out computing power. There are also the two giant AI labs, OpenAI and Anthropic.
- There's huge money on the line: Together these companies have a combined market cap of $50 trillion — more than double what it was five years ago — and nearly $6 trillion in debt.
The intrigue: The market is a bit of a closed loop. A lot of the money circulates among the same group of companies. They finance one another, buy from one another and invest in each other.
- The money circulates like air through an office HVAC system. "Capital, product and demand chase each other around the same handful of names," the authors wrote.
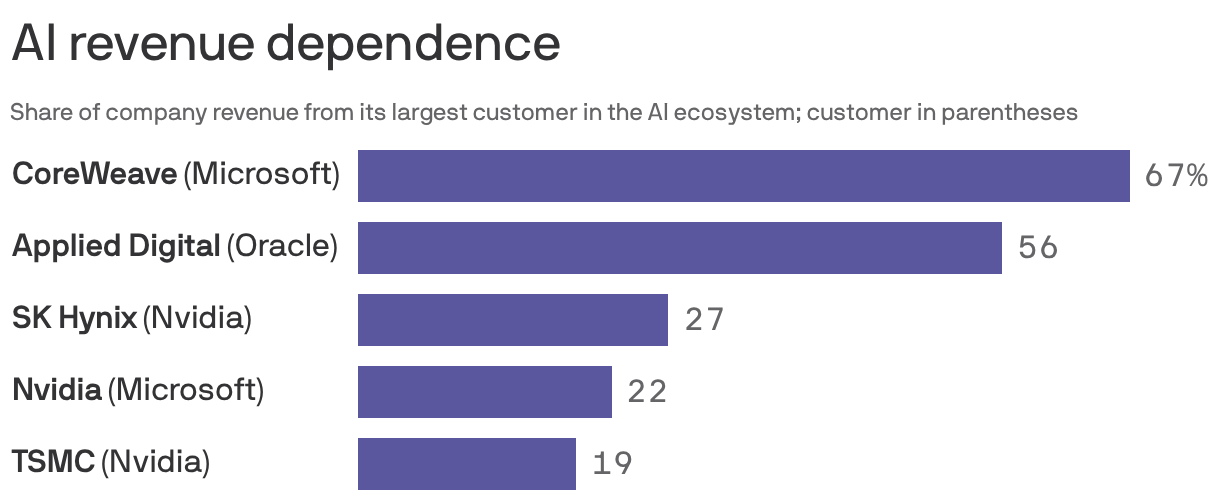
Zoom in: Some of these smaller businesses earn a large share of revenue from just one or two big companies.
- CoreWeave is drawing about 67% of its revenue from Microsoft alone.
- Applied Digital, a data center infrastructure company, gets 56% of its revenue from Oracle and 30% from CoreWeave, which in turn is heavily dependent on Microsoft.
Reality check: That kind of circularity isn't necessarily nefarious, as anyone who's bought a car and tapped financing through a dealer knows.
- The core of the ecosystem — the big hyperscalers, chipmakers and memory companies — is in good financial shape. They generate a lot of cash and have strong credit ratings.
- Unlike in the mortgage crisis, this time individuals and their lives and homes aren't on the line.
- And many of these companies are involved in building and selling real, physical assets — not creating synthetic leverage, the Sona authors note.
Friction point: The financial risks lie "one ring out from the core," with the neoclouds and data center platforms that carry the highest leverage, thinnest margins and weakest cash flows.
- They are at risk if tech advances cause the price of compute to fall.
Between the lines: A single investment decision by a bigger company may be "existential" for these firms, the authors write.
The bottom line: The AI boom is a big, tangled, delicate web.
2. For policymakers, markets are a tough crowd
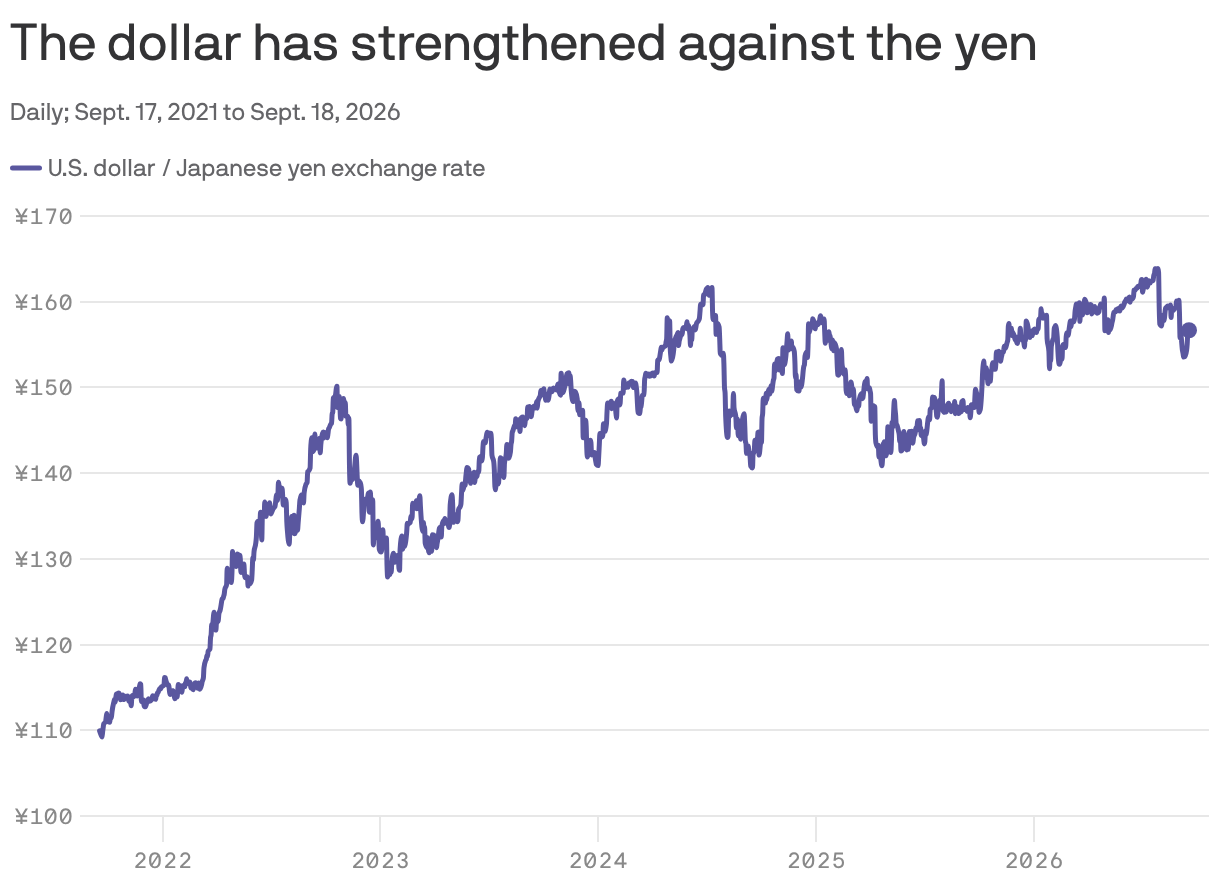
Currency traders largely shrugged off the Bank of Japan's decision to raise its key interest rate to a 31-year high Friday.
Why it matters: It's the latest example of the challenge economic officials face in managing markets that are increasingly jumpy about inflation and large government debts in what seems to be a new, higher-interest-rate environment for the world economy.
Zoom out: In recent months, the U.S. government bond market panned a major press conference of recently installed Federal Reserve chairman Kevin Warsh in late July, contributing to a sharp uptick in Treasury yields. (Warsh's performance as part of last week's Fed rate hike seemed to receive more positive reviews from the markets.)
- Likewise, U.S. Treasury Secretary Scott Bessent's unusual approach to buying back long-term U.S. Treasurys — widely seen as an effort to push down yields — also failed to move the market for more than a moment or so.
The latest: The Bank of Japan raised its key interest rate to 1.25% in part to cool inflation and bolster the strength of the yen, which is down more than 5.5% against the U.S. dollar over the last 12 months.
Reality check: That's a big move for the currency of one of the world's largest economies.
- The weakness of the currency worsens inflation for an import-reliant economy like Japan.
- It hit a 40-year low against the U.S. dollar in July.
- The weakness prompted Japan's Ministry of Finance to intervene in currency markets earlier in the year, including an unusual joint coordination with the U.S. on July 31.
How it works: All else equal, higher central bank interest rates are supposed to attract global capital to a country. That can also help stabilize a weakening currency.
Yes, but: The yen still stumbled after the decision was announced last week, as comments from Bank of Japan governor Kazuo Ueda weren't definitive enough to convince traders that the BoJ would make the hard decisions — that is, keep raising rates when they are already at multi-decade highs — to shore up the yen, if required to do so.
What they're saying: "Ueda was as usual too balanced to send an unequivocally hawkish message," wrote Evercore ISI analyst Krishna Guha. "The result was that while the BoJ certainly did shift hawkish, it was not enough to meet market expectations."
The bottom line: For economic policymakers trying to face down jumpy markets at the moment, everybody's a critic.
Axios Markets