Axios Markets
October 26, 2026
1 big thing: Investors buckle up
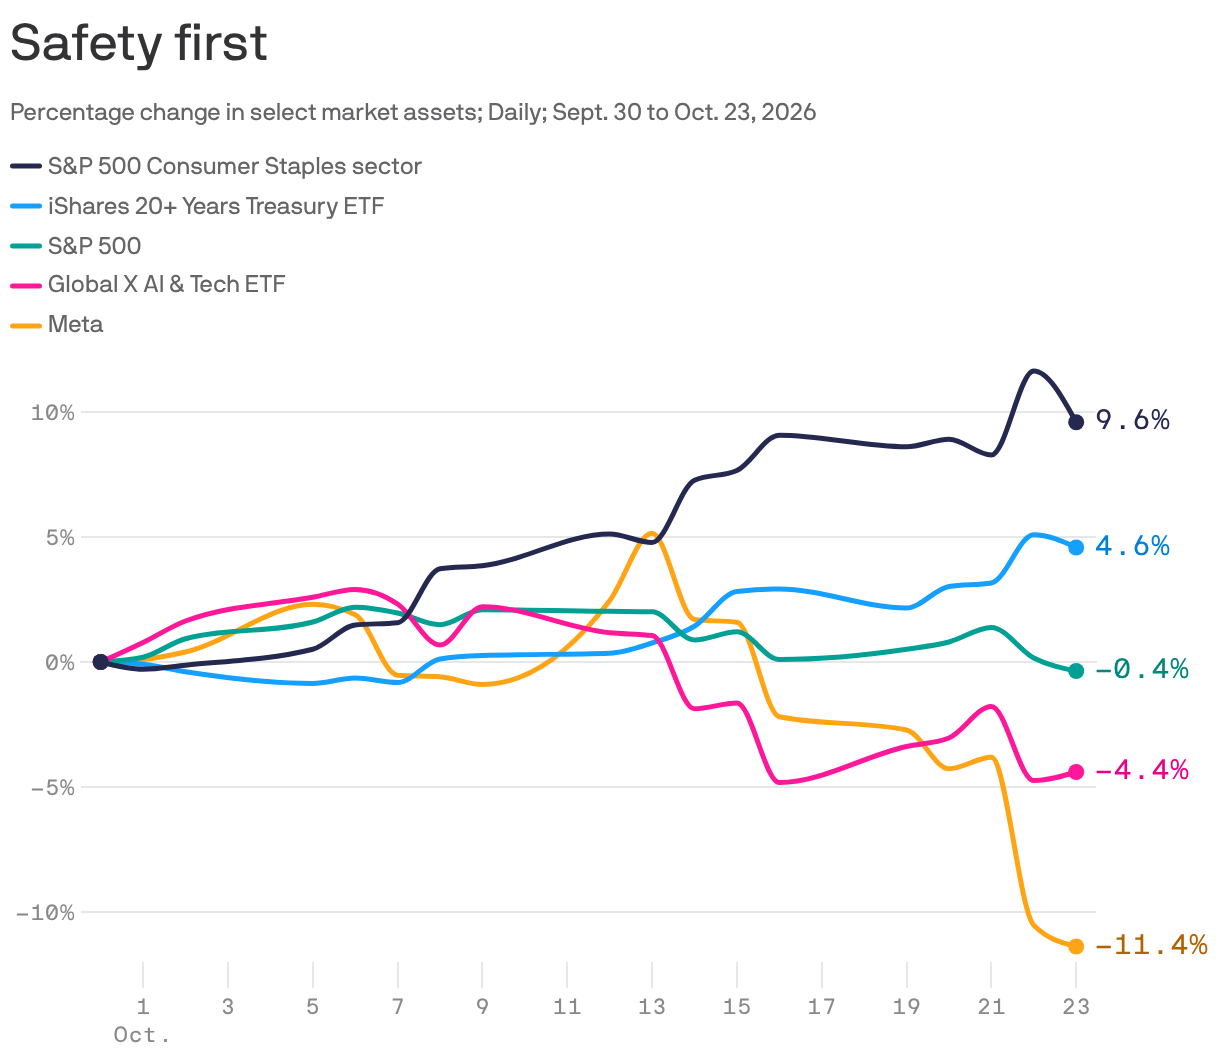
Investors rushed for cover last week in the face of economic, political and market turmoil.
Why it matters: The scramble for safety in both stock and bond markets suggests investors see reducing risk as the simplest response to the crosscurrents — at least for now.
The latest: Yields on U.S. 10-year Treasury notes — which earlier this month hit their highest level in decades at more than 5.30% — plunged to below 5% late last week before finishing at 5%. (Bond yields fall when bond prices rise, and vice versa.)
- Meanwhile, a slump in giant tech stocks — whose large market capitalizations give them enormous sway over cap-weighted indexes like the S&P 500 — resulted in stark outperformance for the less-AI-pilled S&P 500 equal-weighted index.
- On Thursday, the equal-weighted S&P 500 outperformed by nearly 2 percentage points — the biggest gap between the two versions of the blue chips since July 2024.
State of play: The AI investment boom remains a source of anxiety for investors.
- For instance, Meta shares got trounced last week even after it reported much better-than-expected third-quarter sales and profit.
- The issue, it seemed, was the company's unspecified plans to spend "aggressively" on AI, despite the increasingly visible impact such investment is having on the numbers. (Remarkably, Meta's quarterly free cash flow actually went negative in Q3.)
- Other tech behemoths also slumped during the week. Alphabet dropped 6%, while chip giants Nvidia and Broadcom also finished the week in the red.
The big picture: Investors are simply growing more skeptical that the AI investment boom can keep rolling at its current clip. After all, the expenditures that are expected over the next year will have to be heavily financed by the corporate bond market.
- And the corporate bond market is clearly signaling — through higher yields on AI plays such as CoreWeave, for one thing — that raising more cash isn't going to be quite as easy as it has been.
- Those closely watched CoreWeave bonds continued yielding more than 15% on Friday. Credit default swaps on Oracle — the most heavily indebted of the hyperscalers — touched new highs last week.
- More broadly, corporate bond spreads — which widen as investors grow more leery of risk — are at 17-month highs, according to Bloomberg.
Reality check: Caution makes sense — especially if one remembers that there's an entire non-AI world out there, where some pretty big things are happening that could also have huge implications for the markets.
- For instance, it's not crazy to think that if Democrats retake one or both houses of Congress in the Nov. 3 midterm elections — as polling indicates — it could mean more regulatory attention focused on AI.
- That would be a big shift from the Trump administration's largely laissez-faire approach to the technology, branding considerations aside.
- Then there's the risk of the elections themselves, and the chance that Democratic wins set off lawsuits and efforts to undo election results led by the White House and congressional allies. Such activities would, at a minimum, extend a cloud of election-related uncertainty over the markets well past early November.
The bottom line: You can understand how some might see stuffing cash into Treasurys as the easiest course to pursue in the face of all this.
- And that's before considering that you can get inflation-adjusted returns of 2.65% on the 10-year Treasury inflation-protected security, or TIP.
2. The oil risk premium shoots up


Oil prices are back to the high levels of March as investors price in the growing risk that the Iran war will escalate.
Why it matters: Higher energy prices ripple through the entire economy, pushing up inflation.
- The recent rise in oil has also put stocks under pressure: Both the S&P 500 and Nasdaq declined last week as prices climbed.
Where it stands: Last night, when the oil market opened, the price of a barrel of Brent crude for December delivery fell slightly to $115 — after closing in the previous trading session at its highest price since April.
Catch up quick: Just over the last week, the price had already spiked nearly 7% in reaction to reports that the U.S. and Israel plan to restart attacks after the midterms.
Between the lines: The gains appear to be due to what energy analysts are calling a "geopolitical risk premium." That's because the supply of oil from the Persian Gulf region is nearly back to pre-war levels, according to September data analyzed by Robin Brooks, an economist at the Brookings Institution.
- And demand hasn't moved up in any meaningful way.
- "A very large" risk premium is getting priced in, Brooks wrote.
- "Oil is once again flowing from the Middle East," JPMorgan commodity analysts wrote in a note last week.
The intrigue: JPMorgan's pricing model puts Brent's fair value at just $94 per barrel, given the supply-demand dynamics in the market.
- Yet Brent is trading about $20 higher.
Context: These are "futures" prices — investors are valuing what they think a barrel of oil for delivery would go for in December 2026.
- The price reflects "what the market is willing to pay for the possibility that tomorrow's supply may once again be disrupted," the bank noted.
What to watch: Under the hood, there's another dynamic at play that's not showing up in the benchmark price: Soaring shipping costs are driving a wide disparity in the prices that buyers pay for oil around the world, the JPMorgan analysts said.
- Before the war, the price of crude oil in different regions used to more closely track the benchmark, which doesn't include shipping costs.
- Now, there are wide differences as some producers actually lower the price of oil to compensate refiners for high freight costs and to keep them buying.
How it works: For example, oil bound for Asia averaged $93 per barrel before shipping in October, down from $106 in April. But its delivered costs rose to $131 from $116.
- "Geography is reshaping the relative value of crude around the world," explained Natasha Kaneva, head of global commodities research at JPMorgan, on a podcast Friday.
Axios Markets
Stay on top of the latest market trends and economic insights