Big Tech's AI flex gets mixed reviews

Add Axios as your preferred source to
see more of our stories on Google.
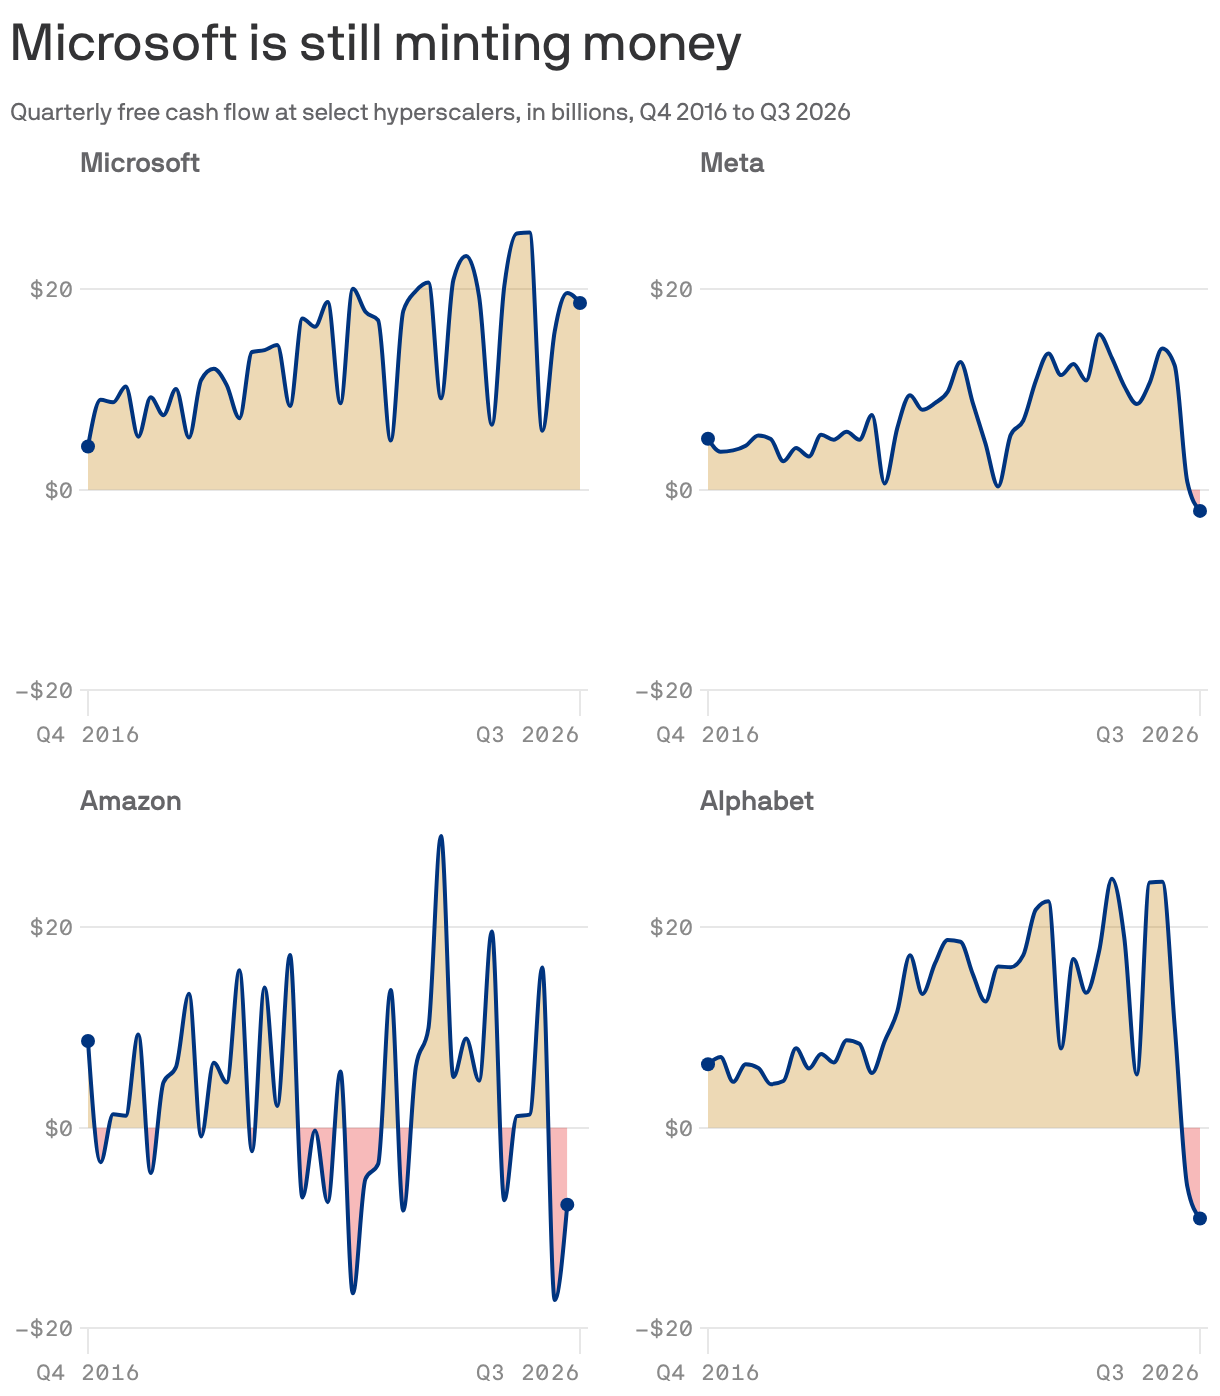
If you're making big bets on AI, you better have the revenue and cash flows to back it up.
The big picture: Starkly different market reactions to quarterly results from Microsoft and Google parent Alphabet illustrate the attributes that investors appear to be valuing at the moment.
The latest: Microsoft shares surged after hours Wednesday as sales and earnings per share for the quarter that ended Sept. 30 both beat analyst expectations.
- Quarterly free cash flow — a key measure of the company's ability to continue pouring money into AI investments without consuming all its own cash — declined about 27% from the prior year to $18.63 billion.
- But that was better than the $7.99 billion expected by analysts, according to FactSet.
- Most importantly, it's still very much in positive territory, unlike other hyperscalers.
Alphabet, however, reported quarterly revenue that fell slightly short of expectations, as did its earnings per share.
- What's more, its free cash flow was even worse than expected at negative $9.1 billion. (Wall Street analysts expected negative $2.23 billion in free cash flow, according to FactSet.)
- Its shares tumbled 11% after hours.
The bottom line: The markets don't seem to mind big AI bets if revenues come through and if capital expenditure doesn't consume all the company's operational cash flow.
- But the results from Alphabet — once one of the greatest cash-producing entities in history — suggest that it is getting increasingly difficult to do.
