Bond investors have gotten picky about AI

Add Axios as your preferred source to
see more of our stories on Google.
Even as AI borrowing roars on, the bond market is becoming more selective about which companies, projects and structures to finance.
Why it matters: Bond markets determine borrowing costs.
- And since the AI boom increasingly relies on debt, borrowing costs have become a key constraint.
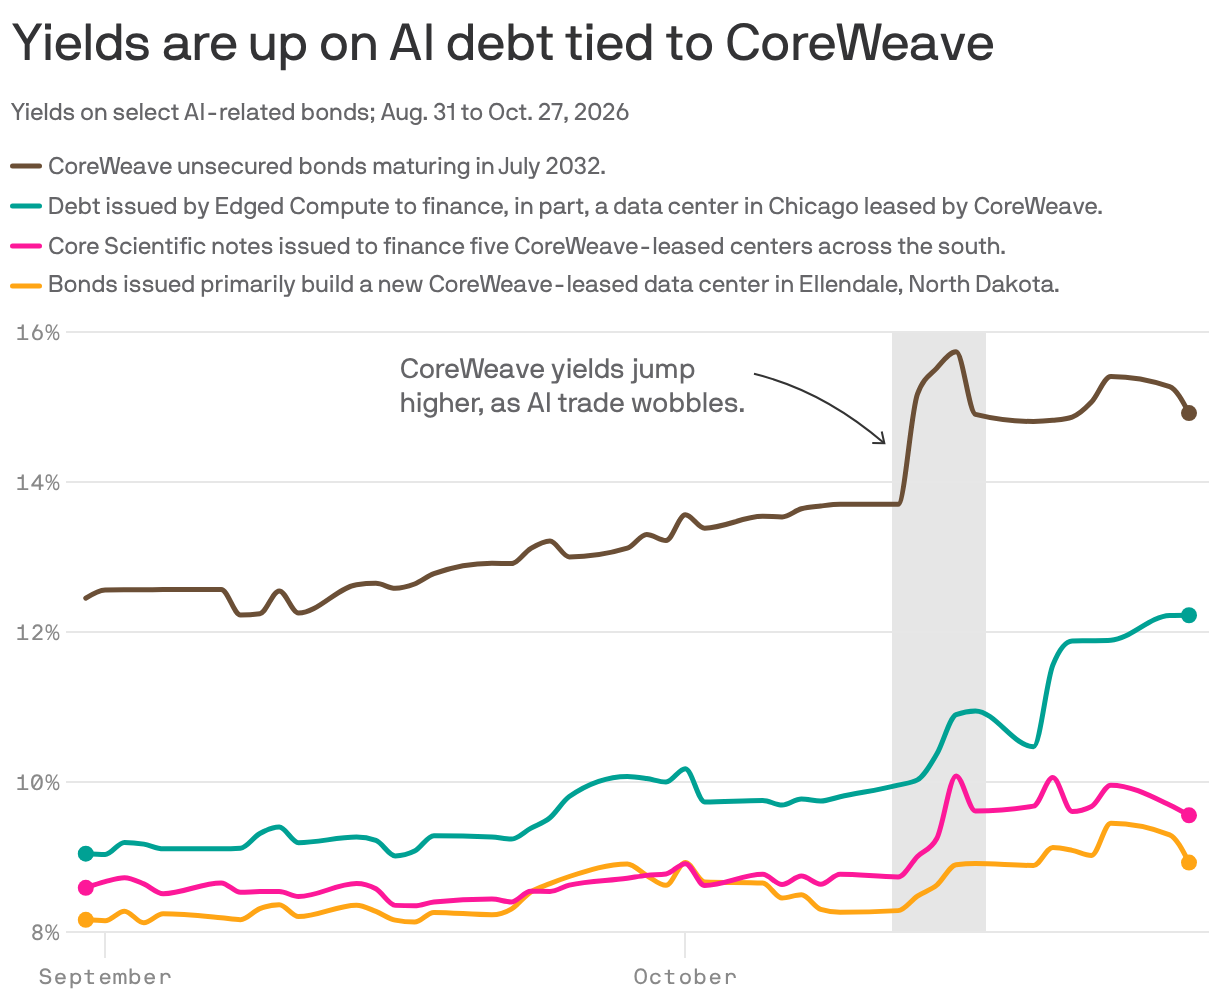
State of play: On the surface, things have calmed down in the corporate bond market since earlier this month, when yields on bonds issued by the heavily indebted AI player CoreWeave soared. (Bond yields move in the opposite direction of their prices, so this means CoreWeave's bond prices tumbled.)
- That calm — plus the excitement over Anthropic and Meta — has helped rebuild confidence in the AI trade that is supporting the stock market.
Yes, but: A CoreWeave-shaped dent remains in the bond market.
- Prices show that investors are increasingly cognizant of the complex web of loans, ownership stakes, lease commitments and contractual obligations linking various players in the boom.
- And assets with links to the most heavily indebted players in the AI ecosystem, like CoreWeave and Oracle, are clearly seeing investors apply a chunky risk premium.
Case in point: After CoreWeave bonds tumbled two weeks ago, pushing yields on its own unsecured bonds to highs of around 16%, bonds that are financing the development of data centers that CoreWeave has leased — including those issued by developer Edged Compute and ex-bitcoin miners Core Scientific and Applied Digital — also saw yields creeping higher. (See the chart, above.)
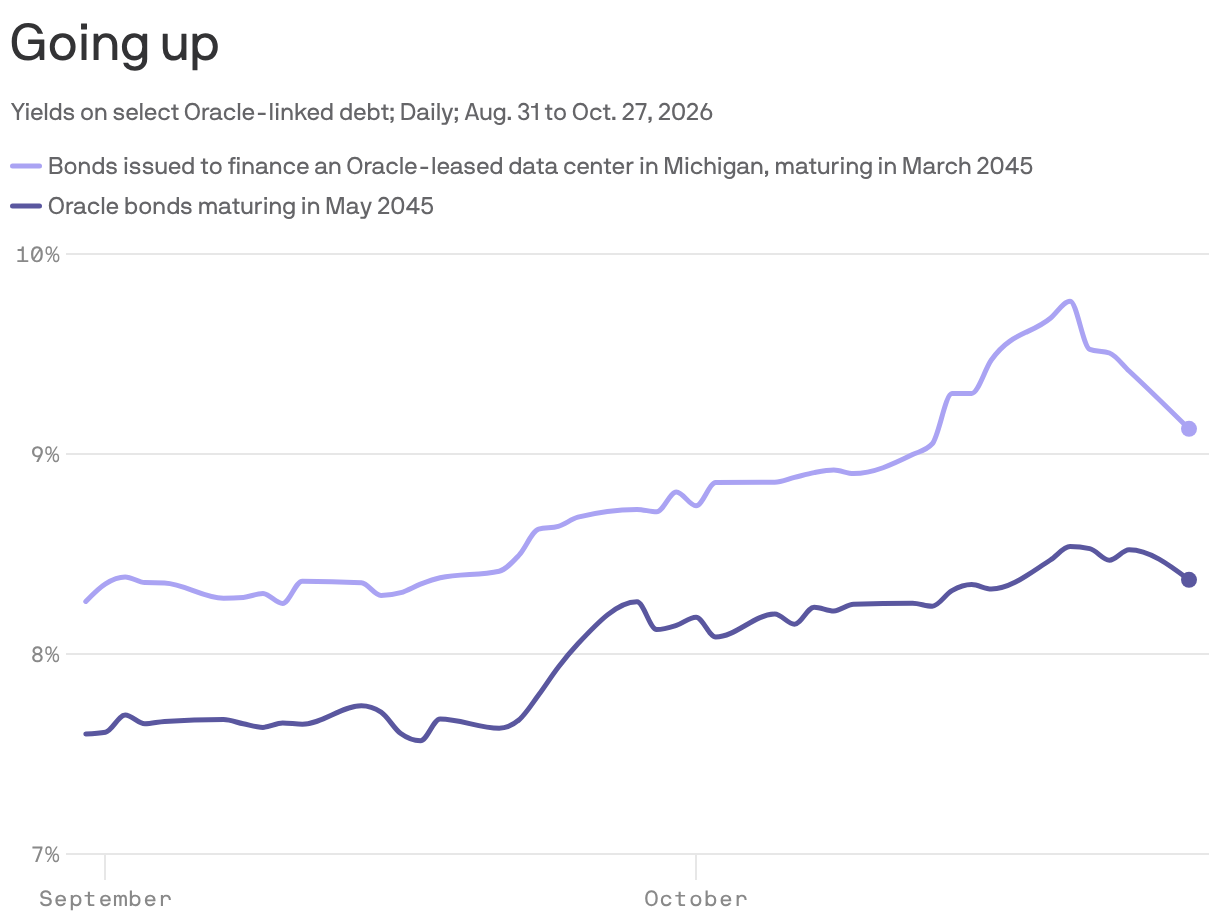
- Likewise, the yields on the debt of data centers contracted to Oracle have moved in sympathy with swings in the price of bonds issued by the heavily indebted hyperscaler itself.
- For instance, yields on roughly $14 billion worth of bonds maturing in 2045 issued to pay for the construction of a large data center campus in Saline Township, Michigan, wobbled alongside those of Oracle over the last couple of weeks. (Oracle's signed 17-year lease for the data center is a major supporting element of the bonds, ratings agencies say.)
What they're saying: "Tenant-specific risk was exposed during the October pullback, with CoreWeave and its associated neoclouds and data centers bearing the brunt of the selloff," wrote high-yield debt analysts at Citigroup last week, adding that data center bonds "are not immune to tenant default risk and can reprice quickly as that risk escalates."
- The story is largely the same in the world of safer investment grade debt, where the market has gone from treating AI-related bonds as somewhat interchangeable to differentiating starkly between different borrowers and bonds.
- "The market has moved from trading AI as a theme to pricing issuers differently," analysts at Barclays wrote.
The bottom line: "We expect differentiation to persist as investors refine their views on the winners and losers of AI spending," the analysts said.
