Rise in yields takes some shine off stocks

Add Axios as your preferred source to
see more of our stories on Google.
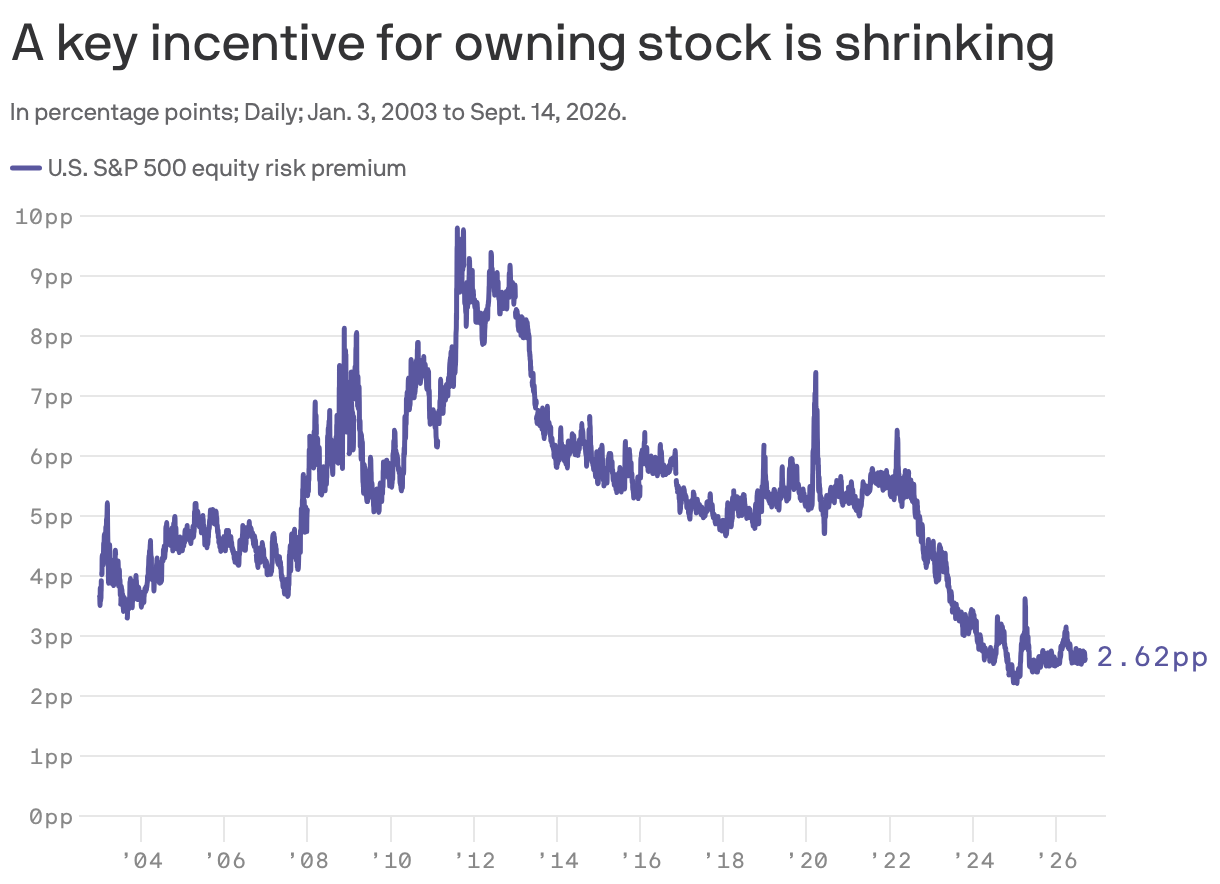
The recent surge in bond yields is keeping the pressure on the premium investors earn for taking their chances with stocks rather than bonds.
Why it matters: The skimpiness of the slab of extra returns the market typically offers stock market investors — which is known as the equity risk premium — raises the prospect that, at some point, investors decide they're just not being paid enough to expose themselves to the vagaries of equities.
Reality check: The equity risk premium can't be observed directly, and there are a few different versions of it.
- The proxy we're using, above, is sometimes called the "yield gap." It takes the earnings yield on the S&P 500 (roughly 5.2%) and subtracts the yield on the inflation-adjusted 10-year Treasury note (2.60%).
What they're saying: In a note published last week, analysts at JPMorgan suggested that the low levels of equity risk premiums we're currently seeing typically coincide with a period when stocks are more sensitive to moves in Treasury yields.
- "This greater sensitivity to bond yields, particularly in the event real rates drift higher from current levels, could provide multi-asset investors with an incentive to increase bond allocations," they wrote, adding that "flows from equities to bonds could become more pronounced than those seen in recent years."
The other side: It is worth noting, however, that equity risk premiums have been near multi-decade lows for a couple of years now, and investors haven't suffered much, as excitement over the possible returns to AI has continued to keep investors attached to stocks.
