Axios Macro

October 27, 2026
The Federal Reserve's penultimate policy meeting of 2026 kicked off at 9:30am ET today, with its results — and a Kevin Warsh press conference — out tomorrow afternoon.
- Today, we look at the communications task the Fed chairman has ahead of him.
- Plus, new data that shows the AI-fueled manufacturing boom continues apace.
Situational awareness: U.S. consumer confidence rebounded this month, rising 7.5 points, to 91.7, according to the Conference Board — the highest since June.
- Views of business and job market conditions improved, but inflation concerns persisted and consumers said they planned to cut back on spending.
Today's newsletter, edited by Jeffrey Cane and copy edited by Katie Lewis, is 948 words, a 3.5-minute read.
1 big thing: Warsh has some 'splainin to do tomorrow
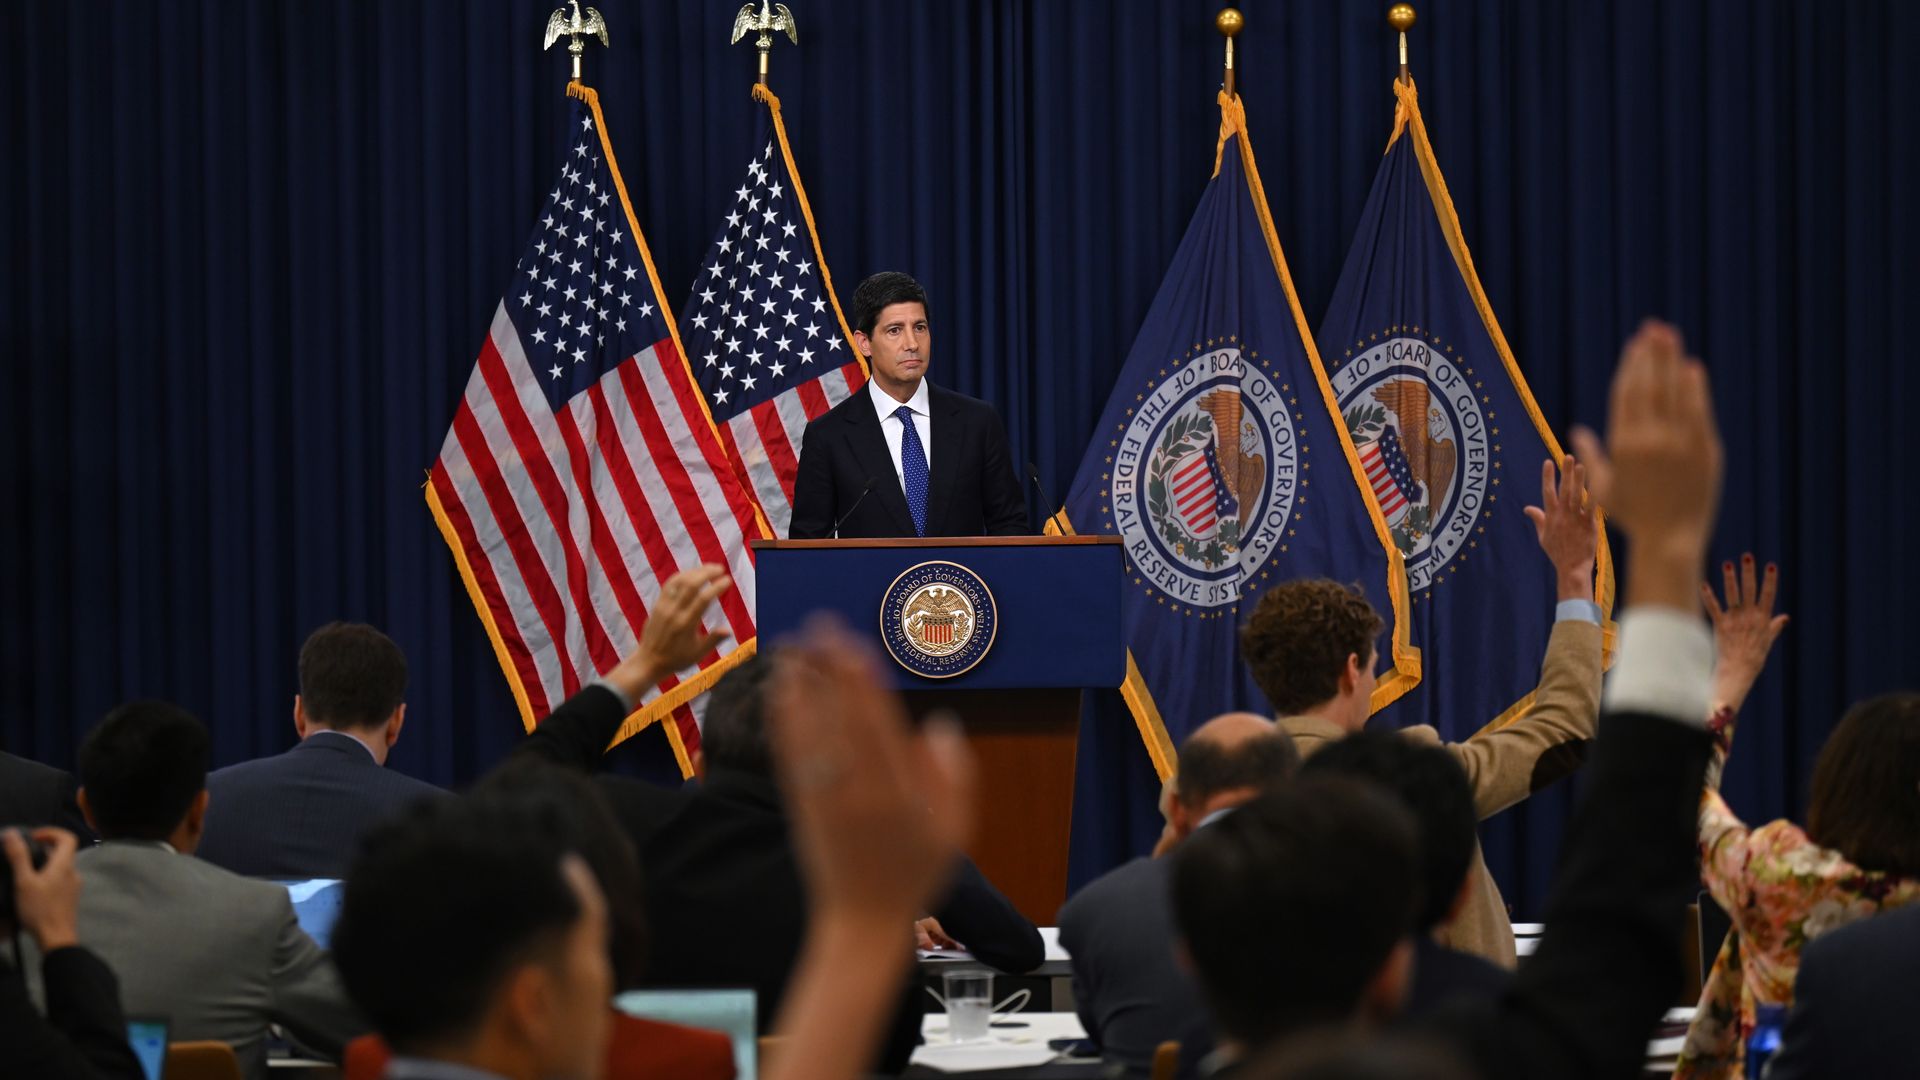
Warsh presents himself as a rock-ribbed central banker prepared to do what it takes to wrestle inflation to the ground.
- If the Fed delivers on expectations tomorrow, he will face a tricky task in reconciling that with non-action in the face of broad price pressures.
The big picture: Since the Fed raised interest rates six weeks ago, incoming inflation data has been hot and energy price pressures have risen. Yet communication from the central bank's leadership has pointed to leaving rates unchanged at this meeting while penciling in another rate hike in December.
- Warsh himself, as is his practice, has refrained from offering much in the way of guidance about what comes next. But barring a surprise rate hike, he will face questions in his news conference about the tension between tough talk on inflation and a policy pause.
- The optics are particularly bad to the extent that it looks as if Warsh is taking a breather from monetary tightening to avoid a move right before the midterm elections.
State of play: The Consumer Price Index and Producer Price Index both came in surprisingly high for September, and energy futures markets now point to more prolonged upward pressure on fuel prices than they did just a few weeks ago.
- The unemployment rate, meanwhile, has remained low and weekly jobless claims have hovered near multidecade lows, suggesting a solid labor market.
- Warsh has emphasized the importance of setting policy not based on individual data prints, but on the broad thrust of data.
- But even some of those measures have indicated broader inflation pressure.
By the numbers: Fitch Ratings calculates that the share of U.S. CPI components for which year-over-year prices have risen more than 3% was 46% in September, twice the share of the low-inflation 2018-2019 period.
- It was considerably lower in the eurozone (36%) and in Canada (32%).
What they're saying: "U.S. inflation breadth began increasing before the recent acceleration in headline inflation," Olu Sonola, head of U.S. economics at Fitch, wrote in a note.
- "This suggests that the rise in inflation is not solely an energy story. Even if energy pressures fade, broader price increases could slow inflation's return to target and keep monetary policy higher for longer."
Of note: The hawkish wing of the Fed's policy committee has started raising those concerns more vocally — and multiple dissents are possible tomorrow.
- "I see inflation pressures as relatively broad-based rather than concentrated in one component," Cleveland Fed president Beth Hammack said earlier this month. "Energy has been making headlines this year, with prices rising for oil, retail gasoline, and diesel, but it isn't the whole story."
- "When I talk with contacts across the District, I hear about additional cost pressures in health insurance, plastics, metals, grains, electricity, and other areas."
Reality check: Whether the Fed raises rates now or in six weeks doesn't matter much for the inflation outlook. And waiting arguably gives the central bank more time to ensure it is not overreacting to a one-time price adjustment.
- Moreover, some wobbles in debt markets funding the AI buildout raise the risk of more trouble ahead for a sector that has propped up overall growth the last couple of years.
- Still, Warsh will want some good answers at the ready as to why his determination on inflation didn't translate into another rate hike this week.
2. Factory momentum


U.S. businesses kept investing heavily in equipment in September, extending a stretch of strong demand for manufactured goods largely fueled by the AI infrastructure boom.
Zoom in: Demand for equipment associated with the AI boom has surged at a pace not seen in recent decades.
- Orders for computers and related products, such as servers, storage devices and peripherals, surged 27% from a year earlier — including a nearly 4% increase in September alone.
- For a faster annual pace of growth, you'd have to go back nearly 30 years to January 1997.
By the numbers: New orders for durable goods rose 1.8% in September, a sharp increase driven by commercial aircraft orders.
- Orders excluding transportation equipment rose 0.5%, as did core capital goods orders, a closely watched measure of business investment that extended a five-month streak of gains.
- Shipments of core capital goods, which feed into GDP estimates of business equipment investment, rose a robust 1.2%.
The intrigue: "Today's report extends the pattern manufacturing has shown since the spring: Investment-led demand is running ahead of what factories can deliver," Richard de Chazal, macro analyst at William Blair, said in a note.
- He added that unfilled orders have risen every month for more than a year, suggesting manufacturers are struggling to keep pace with demand.
What to watch: Thursday's GDP report will show how much the surge in equipment spending contributed to third-quarter growth and whether rising capital goods imports offset that investment.
The bottom line: "The strong AI spending continues to drive business investment, and there are spillovers and strengthening [capital expenditures] outside of tech even amid higher borrowing rates and energy costs," Nationwide chief economist Kathy Bostjancic wrote in a note.
Sign up for Axios Macro