Axios Macro
October 19, 2026
U.S. economic data is in a bit of a lull this week, so we're turning our attention to two big international stories. 🌐
- First: New figures show China's economy is holding up better than expected, but there's a catch.
- Plus: Economic tensions are fueling growing protests in France, with a warning they may hold for policymakers elsewhere.
Today's newsletter, edited by Jeffrey Cane and copy edited by Katie Lewis, is 832 words, a 3-minute read.
1 big thing: China's export juggernaut

China's economy grew faster than expected in the third quarter, extending a yearslong pattern in which surging exports have compensated for weak spending and investment at home.
Why it matters: The stronger that China's economy performs, the less pressure Beijing faces to address the domestic imbalances that have made it so reliant on selling goods abroad.
- But what is working for China is becoming harder for its trading partners to tolerate, raising the prospect that its growth model is reaching political and economic limits overseas.
- The global AI investment boom is helping prop up China's export-driven growth model, though it creates another vulnerability if that spending slows.
By the numbers: China's GDP grew 4.5% in Q3 from a year earlier, up from 4.3% in the second quarter, according to the nation's official statistics. That puts Beijing on track to meet its full-year growth target, which it set at 4.5% to 5% in March.
- Industrial production rose 5.5% in September, far outpacing the 1.1% increase in retail sales, a sign of the persistent imbalance between what China produces and what Chinese consumers buy.
- Property investment plunged 20% in the first nine months of the year, while high-tech manufacturing output surged 14% — reflecting China's shift toward advanced manufacturing.
Between the lines: Fresh trade figures last week show the eye-popping pace at which China is selling goods to the rest of the world.
- Exports surged 36% in September, lifting the country's trade surplus to $938 billion through the first nine months of the year.
- The global AI boom is providing a powerful boost: Chips and computing equipment accounted for roughly a third of China's export growth last month, according to calculations by the Financial Times.
- China is likely set to top last year's $1.2 trillion trade surplus, the largest ever recorded by any country, even as its trading partners grow more concerned about the imbalance.
The big picture: European leaders last week backed plans for a new trade weapon — a "kill switch" — that could allow Brussels to swiftly block Chinese goods or companies from its market.
- It shows the mounting political pressure on one of China's biggest trading partners to protect domestic industries struggling to compete with a flood of Chinese imports.
- The European Union also reached an agreement with China last week to cap imports of Chinese hybrid vehicles at 350,000 annually — less than half the roughly 800,000 shipments projected for this year.
- European Commission president Ursula von der Leyen warned Friday that the EU's trade deficit with China, now exceeding €1 billion a day, is unsustainable and pledged further restrictions on Chinese imports.
- "Our industries have called for action, and we have heard them, and we will respond," von der Leyen said.
The bottom line: "As China's growth looks increasingly imbalanced, a slowdown in the tech capex cycle or new tariff shocks are the key risks to monitor moving forward for the year ahead," Lynn Song, chief economist for greater China at ING, wrote in a note.
2. French doom loop warning
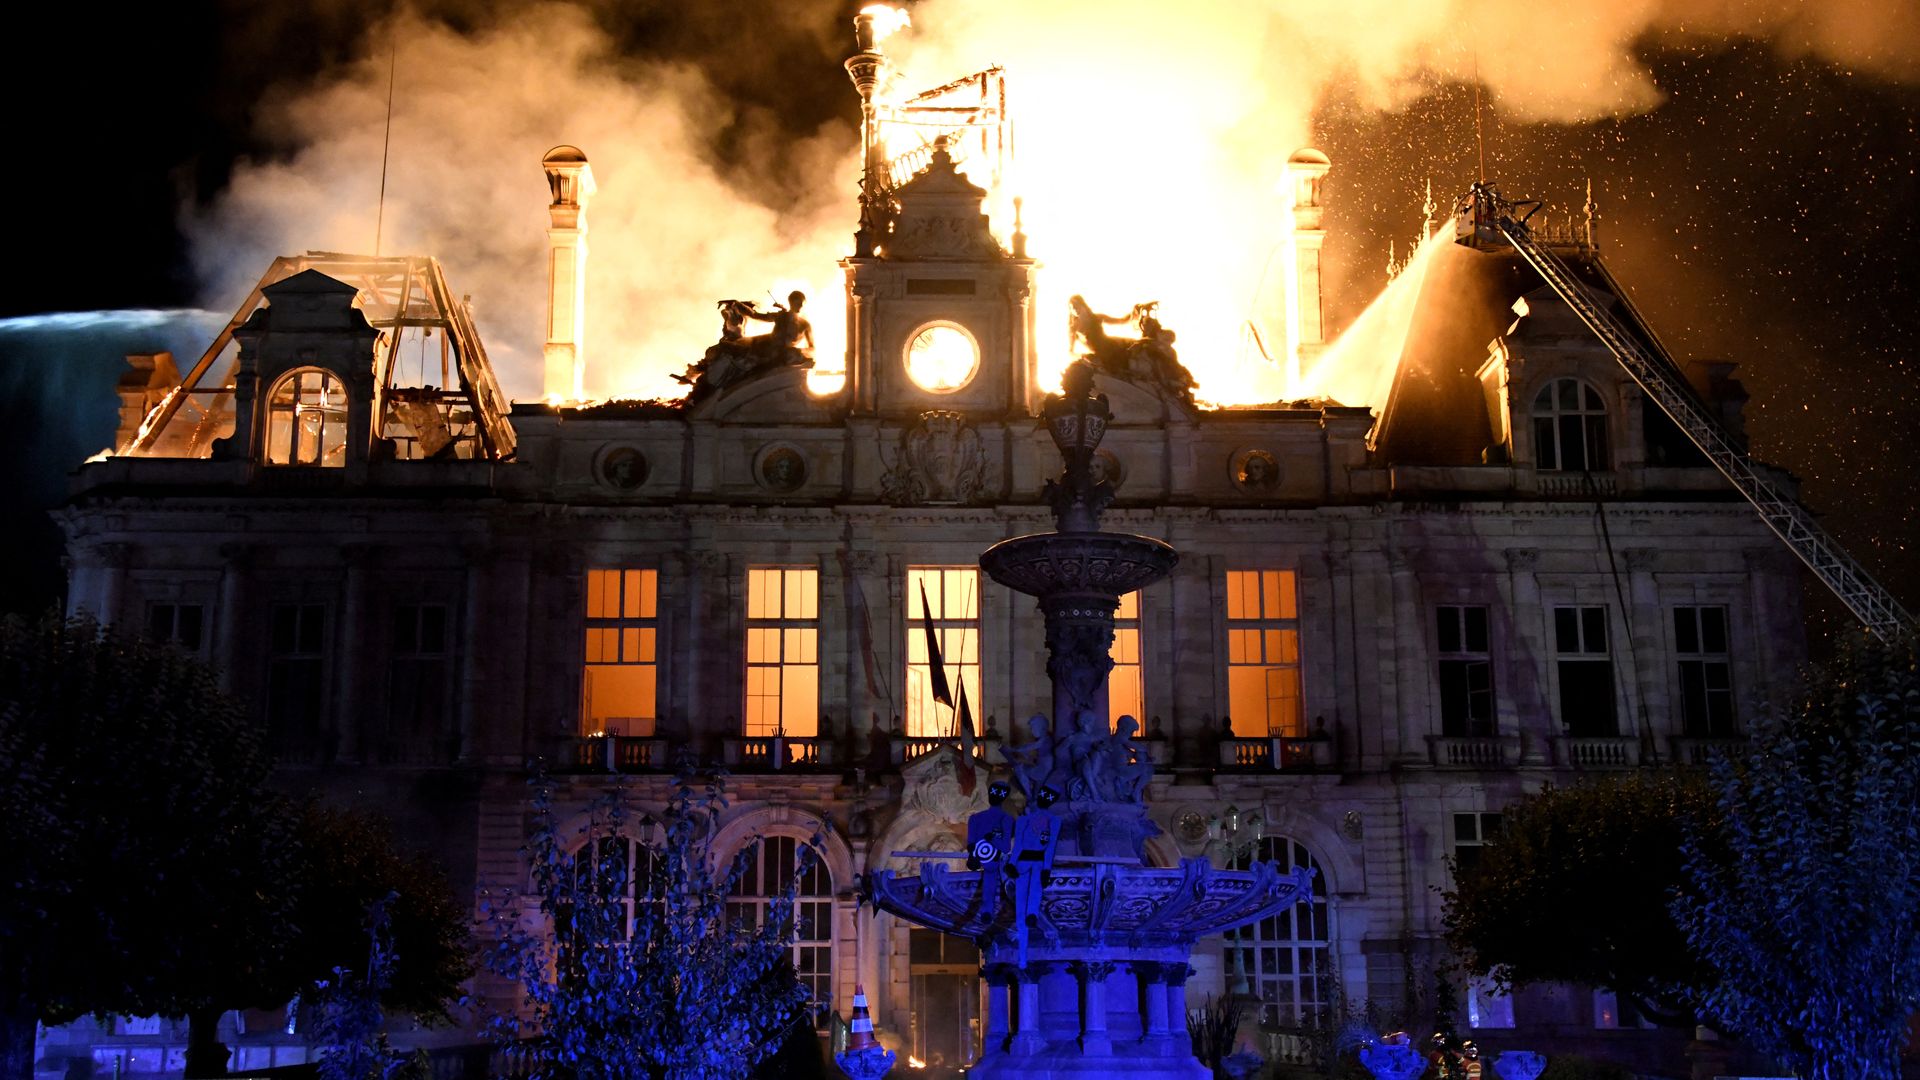
This weekend brought violence in the streets of France. Today brought violence in its bond market. And therein lies a warning for other rich countries staring at big fiscal imbalances.
Driving the news: There were outbursts of violence and looting in several French cities, following demonstrations over school quality and cost of living. They included rioters setting fire to the city hall in Limoges.
- The right-wing National Rally party seized on the events, positioning itself as the party best poised to restore order in elections next year.
- The events drove a new surge in French borrowing costs, with the benchmark 10-year French government bond yield rising 0.15 percentage point today, to 4.93%, flirting with new multidecade highs.
The big picture: The events show the risk of a doom loop among fiscal policy, politics and markets — one that looks particularly ominous in France at the moment but that could equally apply to other advanced economies running large deficits, including the United States and Britain.
- Persistent deficits and rising interest rates compel fiscal austerity, but austerity — especially if it involves cutting pension and other public benefits — is deeply unpopular.
- This toxic unpopularity can cause people to take to the streets, and to elect leaders who promise to maintain benefit levels and defy the fiscal math.
- This generates bond market blowback in the form of higher rates, which makes reining in deficits all the more urgent. Rinse and repeat.
The bottom line: The technocratic challenge of putting major advanced democracies on more sustainable fiscal footing is difficult. But managing the politics is looking downright impossible.
Sign up for Axios Macro